

You need the money — for a consolidation, a repair, an opportunity — and the question crowding everything else out is simple: how fast can I get it? Personal loan timelines vary enormously: some borrowers see funds in a day or two, others wait weeks. The difference is not luck. It is the lender’s process, your preparedness, and a handful of friction points you can control.
This guide explains how long it takes to get a personal loan at each stage — application, approval, and funding — what speeds things up, what slows them down, and how to plan realistically so the money arrives when you actually need it.
Key Takeaways
– A personal loan has three phases: **application** (minutes to hours), **approval/underwriting** (minutes to several days), and **funding** (same-day to several business days).
– Total time ranges from **under 24 hours** (streamlined online lenders, clean applications) to **2+ weeks** (traditional banks, complex cases, verification snags).
– The biggest controllable factor is **your preparation**: complete documents, accurate information, and responsive communication compress every phase.
– Funding speed also depends on *how* you receive the money — direct deposit timing, weekends, and holidays all add days the lender does not control.
– Plan backward from when you need the funds, and never count on the fastest advertised timeline — build in a buffer.
> **A quick note:** This article is for general educational purposes only and is not financial advice. Timelines vary by lender and applicant; treat ranges here as typical, not guaranteed.
## The Three Phases of Getting a Personal Loan
### Phase 1: Application (minutes to a day)
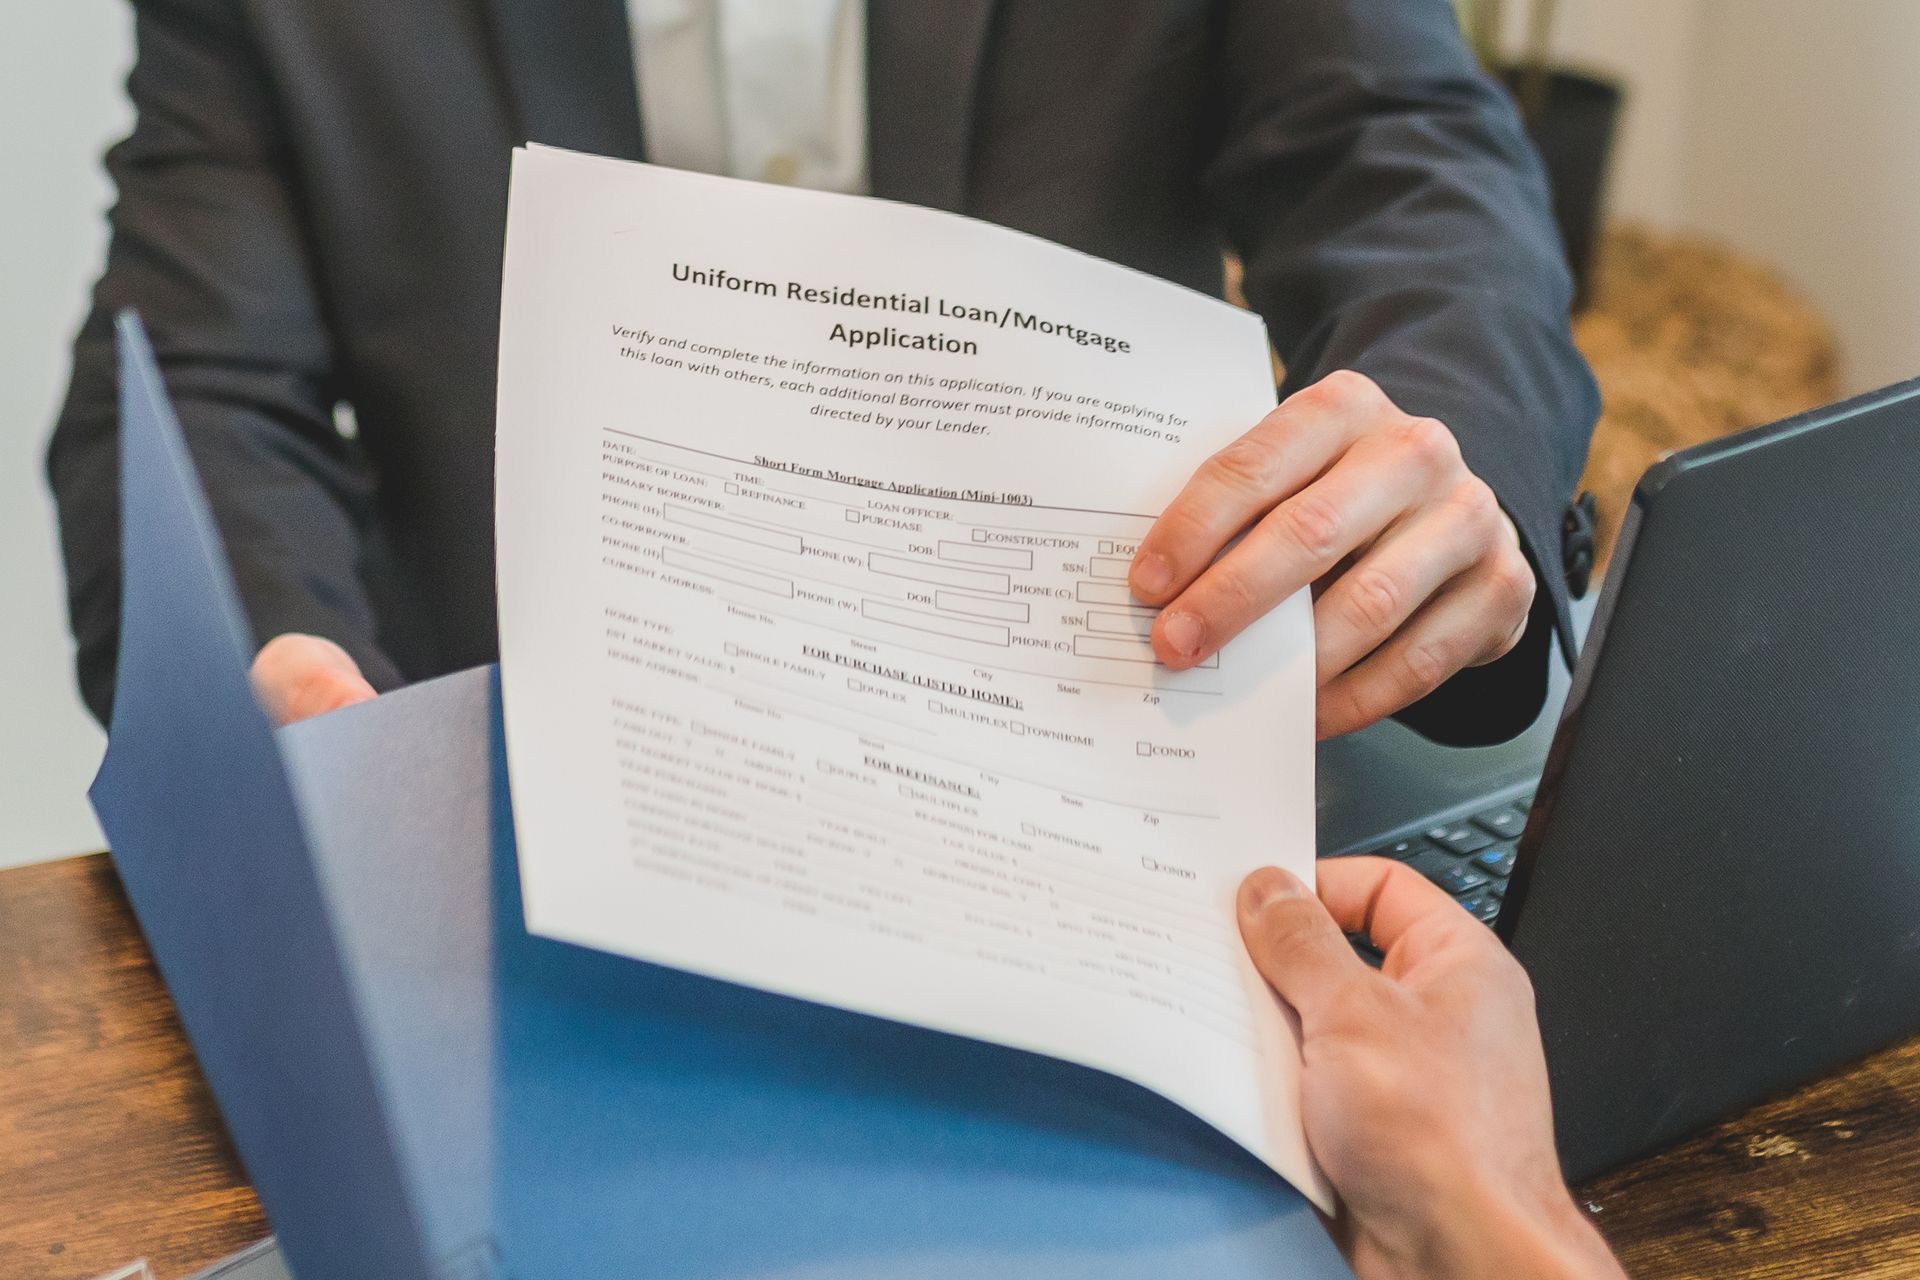
The application itself is the fastest part: personal details, income, employment, housing, the amount requested, and consent for a credit check. Online, this takes 15–30 minutes; in a branch, longer with travel and waiting. The phase extends to “a day” only if you need to gather documents first — which is why our step-by-step application walkthrough (a companion piece) emphasizes assembling paperwork *before* you start the clock.
### Phase 2: Approval and underwriting (minutes to several days)
This is where the variance lives. The lender verifies your identity, income, and employment; pulls your credit; evaluates debt-to-income; and decides. Automated underwriting at online lenders can return decisions in minutes for straightforward applications. Manual review — triggered by complex income (self-employment, multiple sources), thin credit files, large requested amounts, or verification mismatches — stretches to days as humans review documents and ask follow-up questions.
### Phase 3: Funding (same-day to several business days)
After approval, you review and sign the loan agreement (electronically or in person), and the lender disburses. Disbursement to your bank account typically takes 1–3 business days via standard transfer; some lenders offer same-day or next-day funding for applications completed early enough. Weekends and bank holidays pause the clock — a Friday-evening approval often means Tuesday money.
**Typical totals:** best case, under 24 hours from application to funded; common case, 2–5 business days; slow case (traditional bank, manual underwriting, verification issues), 1–3 weeks. Your own experience will fall somewhere on this spectrum depending on the factors above.
## Phase-by-Phase Playbook: Exactly What to Do
**Phase 1 — Application day.** Before touching the application: gather pay stubs (last 30 days), bank statements (2–3 months), government ID, proof of address, and employer contact details. Self-employed? Add the last two tax returns and a year-to-date profit-and-loss. Then apply in one sitting — online, Monday to Thursday morning. Save or screenshot the confirmation and any reference number; note the lender’s stated decision timeline so you can follow up intelligently rather than anxiously.
**Phase 2 — Underwriting.** Your job is responsiveness. Check email and phone (including spam folders) at least twice daily. If the lender requests a document, deliver it the same day — a complete, legible scan, correctly labeled. If a request is unclear, call for clarification immediately rather than guessing and resubmitting. Keep a simple log: date, what was requested, what you sent, confirmation received. This log is also your evidence if timelines slip and you need to escalate.
**Phase 3 — Funding.** The day you sign, confirm in writing: the exact disbursement amount (after any disclosed fee deductions — see our [origination fee guide](https://financeloan.org/16-what-is-an-origination-fee/)), the destination account, the transfer method, and the expected arrival date. Then monitor. If funds do not arrive on schedule, call that day — polite urgency beats passive waiting. Once received, reconcile: does the deposited amount match the agreement? File everything.
## Special Cases That Change the Timeline
**Self-employed and gig workers.** Expect the longest standard timelines. Lenders verify variable income through tax returns and bank-statement analysis rather than a single employer call — inherently slower. Accelerate it by preparing two years of returns, 6–12 months of bank statements, and a clean profit-and-loss *before* applying. Some lenders specialize in non-traditional income; they are worth seeking out.
**Thin credit files.** Few accounts means less data for automated systems, which means manual review. The timeline stretches, and approval odds narrow. If time allows, the fastest fix is not borrowing — it is waiting until the file is stronger. If borrowing cannot wait, expect extra questions and have explanations ready for every account on the file.
**Large requested amounts.** Loans near a lender’s maximum trigger additional verification layers — sometimes a second underwriter or senior approval. The application may also require more documentation (asset statements, detailed debt schedules). Build an extra 3–5 business days into your plan.
**Recent life changes.** New job, recent move, name change — anything that makes your file’s story harder to verify adds manual review time. Bring documentation that bridges the old and new (offer letters, lease agreements, court orders for name changes).
**Joint applications.** Two applicants means two verifications. Timelines roughly follow the slower of the two files — prepare both packages completely.
## When Speed Doesn’t Matter — and When It’s a Trap
Not every borrowing decision should be optimized for speed. If the need is flexible (a planned consolidation, a non-urgent project), a slower lender with better total cost beats a fast lender with worse pricing — the [total-cost worksheet](https://financeloan.org/25-what-is-the-total-cost-of-a-loan/) will show you exactly how much patience is worth.
And beware the urgency trap: manufactured time pressure (“this rate expires today!”, “only 2 loans left at this price!”) is a sales tactic, not a market reality. Legitimate lenders honor quoted terms through stated lock periods; illegitimate pressure is information about the lender, not the market. The borrower who was “too rushed to compare” is the borrower who overpays — our [fee-spotting guide](https://financeloan.org/16-what-is-an-origination-fee/) exists precisely for the moment when speed tempts you to skim.
The healthy mindset: **move fast on preparation, stay deliberate on decision.** Days spent gathering documents are never wasted; minutes skipped reading the agreement sometimes are.
## What Speeds Things Up
**Apply with complete documentation ready.** Pay stubs, bank statements, ID, proof of address — everything the lender lists, gathered before you apply. Each missing document triggers a request-and-wait cycle that costs days.
**Be accurate and consistent.** Your application, your documents, and your credit file should tell the same story: same employer name, same income figures, same address history. Inconsistencies trigger manual verification — the slowest part of underwriting.
**Choose a lender built for speed.** Online lenders with automated underwriting are structurally faster than branch-based banks with committee reviews. If speed is the priority, weight the lender’s process as heavily as its rate — then compare total cost across the fast options using our [total-cost method](https://financeloan.org/25-what-is-the-total-cost-of-a-loan/).
**Apply early in the day, early in the week.** Applications submitted Monday morning enter the pipeline immediately; Friday-afternoon applications sit until Monday. Same-day funding cutoffs are real — miss the cutoff and you wait another business day.
**Respond instantly to lender requests.** Underwriters work queues; when they ask for a document, the application pauses until you deliver. Treat every lender message as urgent — because for your timeline, it is.
**Use electronic signing and direct deposit.** E-signatures eliminate mail and branch-visit delays; direct deposit beats mailed checks by days.
**Keep your bank account ready.** The funding account should be open, in your name, and able to receive the transfer amount. A brand-new account or mismatched names trigger fraud checks that add days.
## What Slows Things Down
**Incomplete or inconsistent applications.** The #1 delay, by far. Every gap becomes a round-trip of questions.
**Manual income verification.** Self-employment, gig income, bonuses, rental income — anything beyond a simple W-2 salary takes longer to verify. Lenders may ask for tax returns, profit-and-loss statements, or bank-statement analysis. Prepare these upfront if your income is non-standard.
**Credit file complications.** Thin files, recent negative marks, or identity-verification flags (address mismatches, fraud alerts) push applications into manual review. If you know your file has quirks, address them before applying — our guide to [what credit score lenders expect](https://financeloan.org/19-what-credit-score-do-you-need-for-a-loan/) helps you assess where you stand.
**Large requested amounts.** Bigger loans get more scrutiny — additional verification, sometimes senior approval. If you are near a lender’s maximum, expect extra steps.
**Collateral or special structures.** Most personal loans are unsecured, but if yours involves any special terms, each adds review time.
**Bank holidays and weekends.** The calendar is indifferent to your urgency. Plan around holidays explicitly.
**Fraud and compliance holds.** Identity verification failures, sanctions-list checks, or anti-money-laundering flags can freeze an application for days while compliance teams review. Accurate, consistent information is the best prevention.
**Your own hesitation.** Borrowers sometimes stall at the signing stage — re-reading, second-guessing, waiting for a “better” offer. Due diligence is wise (read every fee with our [origination fee guide](https://financeloan.org/16-what-is-an-origination-fee/) open beside you), but once you have decided, sign promptly — the clock does not pause for deliberation.
## Lender Types and Their Typical Speeds
**Online lenders / fintechs.** Built for speed: automated applications, algorithmic underwriting, e-signatures, fast disbursement. Often the fastest path — same-day to 2 days is common for clean applications. Trade-off: compare their total cost carefully; speed is a feature you may pay for in pricing.
**Traditional banks.** Slower by design: branch processes, manual review layers, sometimes committee approval for larger amounts. 5–10 business days is typical; existing customers with direct deposit sometimes move faster. Trade-off: relationship pricing can be competitive for well-qualified customers.
**Credit unions.** Variable — small ones can be nimble and personal, large ones resemble banks. Often competitive pricing for members. Typical: 3–7 business days.
**What does not change with lender type:** the verification fundamentals. Every legitimate lender verifies identity, income, and creditworthiness. Anyone promising instant money with no verification is not offering a personal loan — they are offering something else, usually at a terrible price.
## The Hidden Time Costs Borrowers Forget
When borrowers estimate timelines, they count the lender’s process and forget their own side of the ledger:
**Document gathering.** The lender’s “2–5 days” starts when your application is *complete*. If gathering tax returns and bank statements takes you a week, your real timeline is a week plus the lender’s days. Start gathering before you need the loan — a standing folder with recent pay stubs, statements, and ID copies turns future applications from week-long scavenger hunts into hour-long tasks.
**Comparison shopping.** Properly comparing 3 offers with the total-cost worksheet takes a few hours of focused work. Borrowers in a hurry skip it — and the skipped comparison is often the most expensive part of the whole loan. Budget the hours; they pay for themselves.
**The cooling-off you should take.** Even when everything looks good, a night’s sleep between final offer and signature is cheap insurance against impulse. Build it into the plan rather than treating it as delay.
**Post-funding tasks.** Setting up autopay, updating your budget, filing the agreement — small tasks that prevent the most common post-loan problems (missed first payments are surprisingly common, usually because the borrower never confirmed the first due date). An hour now prevents fees and credit damage later.
Add these honestly to your backward plan and the timeline stops surprising you.
## Planning Backward: A Practical Timeline Worksheet
Do not ask “how fast can it go?” Ask “when do I need the money, and what must happen by when?”
1. **Set your need-by date.** When must the funds be available? (Bill due date, contractor start, etc.)
2. **Subtract funding time.** Allow 3 business days for disbursement (conservative).
3. **Subtract underwriting time.** Allow 3–5 business days for approval (longer for banks or complex income).
4. **Subtract your preparation time.** How long to gather documents? Be honest.
5. **Add a buffer.** Two extra business days for the unexpected — because something unexpected is the norm, not the exception.
The resulting date is your **apply-by date**. If that date is in the past, you need a faster lender or a renegotiated deadline — better to discover this now than after the bill is overdue. And if the need is truly urgent (days, not weeks), be realistic about whether a personal loan is the right tool at all; our [business line of credit guide](https://financeloan.org/23-what-is-a-business-line-of-credit/) discusses faster facilities for business needs, and for personal emergencies, existing credit lines or negotiated payment plans often beat a rushed new loan.
## After Approval: The Final Stretch
Approval is not funding — a few steps remain, each with its own clock:
– **Review the agreement.** Read it fully *before* signing: payment amount, rate, term, every fee, prepayment terms. Our [fee-spotting routine](https://financeloan.org/16-what-is-an-origination-fee/) applies here. This review is worth an hour; rushing it to save a day is a bad trade.
– **Sign correctly.** E-signatures are instant; wet signatures require branch visits or mail. Follow the lender’s instructions exactly — a mis-signed document restarts the step.
– **Confirm disbursement details.** Verify the destination account and expected timing in writing. Ask: “When will the funds arrive, and how will I know?”
– **Watch for the money.** Track the transfer; if it does not arrive when promised, call immediately — do not assume “it is processing.”
– **Check what you received vs. what you signed for.** Confirm the deposited amount matches the agreement *after* any disclosed fee deductions. Discrepancies get harder to dispute with time.
## Frequently Asked Questions
### Can I really get a personal loan the same day I apply?
Sometimes — with streamlined online lenders, clean documentation, early-day application, and same-day funding options, under-24-hour funding happens. But it is the best case, not the promise. Plan for several days and be pleasantly surprised.
### Does a faster loan cost more?
Often, yes — though not always. Lenders optimized for speed sometimes price higher, and urgency makes borrowers compare less carefully (which is itself expensive). Always run the [total-cost comparison](https://financeloan.org/25-what-is-the-total-cost-of-a-loan/) even when you are in a hurry — especially when you are in a hurry.
### Will applying to multiple lenders slow things down?
Each application takes time and may add a hard inquiry. A smarter approach: research and shortlist 2–3 lenders, prepare one complete document package, and apply in a focused window. Shotgun applications cost time and inquiries without improving odds.
### What if I need the money by a hard deadline?
Apply immediately to the fastest credible lender, prepare documents today, and simultaneously negotiate the deadline if possible (creditors, contractors, and providers often grant short extensions when asked early). Parallel paths beat single bets.
### Do weekends count in funding timelines?
No — “business days” exclude weekends and bank holidays at every stage after application. A Thursday approval with 2-business-day funding means Monday money, not Saturday.
### Can I speed up underwriting by calling the lender?
Sometimes, marginally — a call can clarify a document request faster than email tag. But underwriting queues are queues; no amount of calling makes verification instantaneous. The real speed lever is submitting a complete, consistent application in the first place.
### Does pre-qualification speed up the final loan?
Pre-qualification (a soft-inquiry estimate) does not underwrite you — but it does let you shortlist lenders efficiently, so the formal application goes to the right place the first time. Think of it as route planning: it does not make the car faster, but it avoids wrong turns.
### If I’m denied, how soon can I reapply elsewhere?
Immediately, in most cases — but pause first and find out *why*. Reapplying blindly repeats the failure and accumulates hard inquiries. Get the reason (lenders must provide adverse-action notices explaining declines), address it if you can, then target a lender whose criteria fit your profile. Our [credit score guide](https://financeloan.org/19-what-credit-score-do-you-need-for-a-loan/) helps you match yourself to the right tier of lender.
## Conclusion: How Long It Takes to Get a Personal Loan — and How to Control It
**How long does it take to get a personal loan?** Anywhere from under a day to several weeks — with 2–5 business days the common case. The timeline has three phases (application, approval, funding), and while you cannot control the lender’s machinery, you control the inputs that matter most: complete documents, consistent information, a speed-appropriate lender choice, early-week timing, and instant responsiveness. Plan backward from your need-by date, build in buffer days, and verify every figure in the agreement before you sign — using our [payment formula](https://financeloan.org/20-how-to-calculate-loan-payments/) to check the numbers and our [fee guide](https://financeloan.org/16-what-is-an-origination-fee/) to catch the costs.
Speed is a feature, not the product. The cheapest fast loan still beats the expensive fast loan — so move quickly, but compare completely. And once the money arrives, the timeline mindset should flip entirely: from “how fast can I get it” to “how steadily can I repay it” — because the borrowing sprint is over in days, while the repayment marathon runs for years. Set up autopay before the first due date, keep the agreement where you can find it, and revisit the total-cost worksheet annually as a reminder of what the loan is actually costing you. That is how a fast loan stays a good loan. (Educational content only — not financial advice.)
More practical borrowing timelines in our [Personal Loans](https://financeloan.org/personal-loans/) section — and if you are weighing speed against cost across several offers, the total-cost worksheet will tell you exactly what each day of haste is worth.